by Jobuza Team | Jan 23, 2026 | BLOG, Trending News
Filing your first Income Tax Return (ITR) can seem confusing at first. With multiple forms, deadlines, and tax rules, it’s natural to feel overwhelmed. The good news is that with the right preparation, the process is straightforward and manageable.
This step-by-step guide explains everything a new taxpayer needs to know to file an ITR correctly and on time.
1. Do You Need to File an ITR?
You are required to file an ITR if you meet any of the following conditions:
-
Your total income exceeds the basic exemption limit
-
You own assets in India or abroad
-
You have invested in shares, ESOPs, or other financial markets
-
Your total bank deposits exceed ₹50 lakh in a year
-
The combined balance in your savings or current accounts exceeds ₹1 crore
-
You paid electricity bills of more than ₹1 lakh during the year
-
You spent over ₹2 lakh on foreign travel
-
Your annual business turnover or sales exceed ₹60 lakh, even if profits are lower
Even if tax is not payable, filing an ITR may still be mandatory in many of these cases.
2. Understand Your Total Taxable Income
Your taxable income is calculated by subtracting eligible deductions from your total earnings.
Total earnings may include:
Common deductions include:
-
Contributions to PPF or NPS
-
Life and health insurance premiums
-
Home loan interest
-
Rent paid, if eligible for exemption
Understanding this calculation is key to filing an accurate return.
3. Choose Between the Old and New Tax Regime
India currently offers two tax regimes:
Before filing, compare both options to see which one results in lower tax liability. Using an online tax calculator or consulting a Chartered Accountant can help you make the right choice.
4. Keep Track of the Filing Deadline
For the financial year 2024–25 (assessment year 2025–26):
-
On-time filing: File by 15 September 2025 without penalty
-
Late filing: Returns can be filed until 31 December 2025 with a penalty ranging from ₹1,000 to ₹10,000, depending on income and delay
Missing the deadline can also affect refunds and future compliance.
5. Keep These Documents Ready Before Filing
Having all documents in place makes filing quicker and error-free:
-
Form 16 issued by your employer
-
PAN and Aadhaar card (must be linked)
-
Proof of investments such as PPF, insurance receipts, or fixed deposits
-
Home loan interest certificate, if applicable
-
Receipts for any deductions you plan to claim
6. Understand Your Form 16
Form 16 is issued by your employer and acts as a summary of your salary income. It includes:
Using Form 16 helps ensure your salary details are reported correctly in your ITR.
7. Review Your Form 26AS Carefully
Form 26AS shows all income on which tax has already been deducted, such as salary, interest, or professional fees.
It is important to cross-check this form to avoid mismatches that could delay processing or refunds.
You can access Form 26AS through:
8. Check Your Annual Information Statement (AIS)
The Annual Information Statement provides a consolidated view of your financial activity, including:
Most ITR fields are pre-filled based on AIS data, so reviewing it ensures accuracy.
You can find AIS by logging into the Income Tax e-filing portal and selecting it under the “Services” section.
9. Complete E-Verification After Filing
Submitting the ITR is not enough. You must e-verify it within 30 days, or the return may be treated as invalid.
You can e-verify using:
E-verification is essential for faster processing and timely refunds.
10. Select the Correct ITR Form
Choosing the right form is crucial:
-
ITR-1: Salary income, one house property, and other sources
-
ITR-2: Individuals or HUFs without business income
-
ITR-3: Individuals or HUFs with business or professional income
-
ITR-4: Presumptive income from business or profession
Selecting the wrong form can lead to rejection or notices from the tax department.
Final Word for First-Time Filers
Filing your ITR on time helps you avoid penalties and builds a clean financial record. This can be useful when applying for loans, visas, or making future investments.
If you are filing for the first time and feel unsure, seeking professional assistance can save time and provide peace of mind. Once you’ve done it once, filing your ITR becomes much easier in the years ahead.
by Jobuza Team | Jan 23, 2026 | BLOG, Trending News
New Delhi: As the Union Budget 2026 approaches, married taxpayers in India may soon have a reason to feel optimistic. The Finance Ministry is reportedly considering an optional joint income tax filing system for married couples, a move that could significantly reduce the tax burden for many households.
If introduced, this system would allow couples to file their income tax returns together instead of separately. The proposal is aimed particularly at single-income families, where one spouse’s tax exemptions and deductions often go unused under the current system.
The idea has been put forward by the Institute of Chartered Accountants of India (ICAI) and draws inspiration from countries such as the United States and Germany, where joint tax filing for married couples is already a well-established practice.
How Income Tax Works for Married Couples at Present
Under India’s existing income tax framework, marriage has no impact on taxation. Each individual is taxed separately, with their own income slabs, exemptions, and deductions.
In households where only one spouse earns, the non-earning spouse’s tax benefits—such as basic exemption limits and deductions—remain unused. This often results in a higher overall tax liability for the family, even when household income is modest.
What Joint Taxation Could Mean Under Budget 2026
To address these concerns, the Union Budget 2026 may introduce an optional joint taxation regime for married couples. Under this proposed system, both spouses could combine their incomes and file a single joint income tax return.
The key feature of the proposal is flexibility. Taxpayers would be free to choose between the existing individual taxation system and the new joint filing option, depending on which is more beneficial.
To ensure transparency and compliance, the joint filing option would be available only if both spouses have valid Permanent Account Numbers (PANs). This safeguard would also ensure that dual-income households are not forced into a less favourable tax structure.
Who Stands to Benefit—and Who May Not
Joint taxation is expected to be especially beneficial for single-income families, as it could allow better use of tax slabs and deductions. Couples may also find it easier to optimise exemptions related to home loan interest, health insurance premiums, and other family-linked expenses.
However, joint filing may not work in favour of everyone. In households where both spouses earn high incomes, combining earnings could push the total income into a higher tax slab or surcharge bracket. In such cases, filing separately may remain the more tax-efficient option.
When Will Union Budget 2026 Be Presented?
Union Finance Minister Nirmala Sitharaman is scheduled to present the Union Budget 2026–27 on Sunday, February 1. The budget is being closely watched by businesses, taxpayers, and industry leaders, especially amid concerns over global economic uncertainty and potential US tariff impacts.
If the joint taxation proposal is announced, it could mark a significant shift in India’s personal tax system and bring long-awaited relief to many married households.
by Jobuza Team | Jan 22, 2026 | BLOG, Trending News
Remove Your Digital Footprint: In today’s digital age, almost everyone uses the internet for searching, shopping, entertainment, and communication. Just like footprints left on sand, every online activity leaves behind a digital footprint. Over time, this data can expose you to risks such as data breaches, identity theft, and hacking.
If you want to protect your privacy, you can reduce or even erase much of your digital footprint. This requires deleting existing data and stopping new data from being collected. Below are five effective and practical steps to help you clean up your online presence.
Step 1: Delete Your Google Activity
Your Google account stores a large amount of personal data, including search history, location details, YouTube activity, and app usage.
To delete this data:
-
Visit myactivity.google.com and sign in to your Google account
-
Click on “Delete activity by”
-
Choose a time range such as Last hour, Last day, or All time
-
Select All time to remove your entire activity history
-
You can also delete data from specific Google services like Search, Maps, or YouTube
This step helps remove a major portion of your online footprint.
Step 2: Stop Google from Tracking Your Activity
Deleting old data is not enough if new data continues to be collected in the background.
To prevent future tracking:
-
Open your Google Account settings
-
Go to the Data & Privacy section
-
Turn off Web & App Activity
-
Disable Location History
-
Turn off YouTube History
These settings stop Google from tracking your searches, app usage, locations, and video activity going forward.
Step 3: Enable Auto-Delete for Stored Data
Google also provides an auto-delete feature that automatically removes your data after a set time period.
To enable this:
-
Visit myactivity.google.com/auto-delete
-
Choose Web & App Activity, Location History, or YouTube History
-
Set auto-delete to 3 months, 18 months, or 36 months
This ensures your data does not stay stored forever and improves long-term privacy.
Step 4: Use a Secure Internet Connection and Browser
Cleaning your data is ineffective if your internet connection remains vulnerable.
To improve online security:
-
Use a trusted VPN to hide your IP address and encrypt your internet traffic
-
Choose privacy-focused search engines like DuckDuckGo, Startpage, or Brave Search
-
Use secure browsers such as Firefox or Tor Browser
-
Avoid logging into sensitive accounts on public Wi-Fi networks
These steps help protect your identity and browsing activity from hackers.
Step 5: Strengthen Your Password and Account Security
Weak passwords are one of the most common causes of hacking.
To secure your accounts:
-
Change your passwords every three to six months
-
Use strong passwords with a mix of letters, numbers, and symbols
-
Avoid using the same password on multiple websites
-
Enable two-factor authentication wherever possible
This greatly reduces the risk of unauthorized access.
Why Reducing Your Digital Footprint Matters
Remove Your Digital Footprint: By following these steps, you reduce the amount of personal data available online. This lowers your chances of being tracked, targeted by advertisers, or hacked. Regularly reviewing your privacy settings and online activity is one of the simplest ways to stay safe in the digital world.
by Jobuza Team | Jan 21, 2026 | BLOG, Trending News
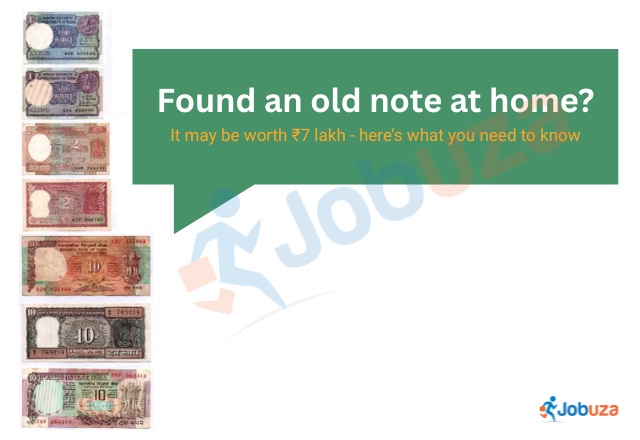
Old currency notes and coins are no longer just reminders of the past. For many collectors, they have turned into valuable assets. In India, interest in rare currency is growing rapidly, and certain old banknotes are now selling for lakhs of rupees.
If you have an old currency note from the pre-independence period lying at home, it may be worth far more than its face value.
The British-Era 1-Rupee Note Creating Buzz
One of the most talked-about rare notes among collectors is the 1-rupee banknote from the British era. Issued around 1935, this note carries the signature of J.W. Kelly, who served as the Governor during that period.
Being nearly 90 years old, this note is considered extremely rare. In recent years, collectors have shown strong interest in owning it, pushing its market value as high as ₹7 lakh in some cases, especially when the note is in excellent condition.
What Makes This 1-Rupee Note So Valuable?
This banknote is not just old; it represents an important phase of India’s financial history. Several factors contribute to its high value among collectors:
-
Historical importance from the British era
-
Limited number of notes still in circulation
-
Signature of the then Governor
-
High demand among currency collectors
-
Well-preserved condition without cuts, stains, or damage
Only notes that are clean, intact, and original fetch premium prices. Any tear, discoloration, or missing part can significantly reduce the value.
Where Are Old Notes and Coins Sold Online?
With the rise of digital platforms, collectors now often buy and sell rare currency online. Websites such as Coin Bazaar and Quikr are commonly used for listing and auctioning old notes and coins.
However, it is important to note that the Reserve Bank of India (RBI) does not officially permit the buying or selling of old banknotes and coins as collectibles. Such transactions are carried out at the buyer’s and seller’s own risk, and individuals should exercise caution.
Why Does a 1-Rupee Note Sell for Lakhs?
The key reason behind the high price is rarity. The 1-rupee note has been discontinued multiple times over the years. As time passed, fewer notes survived in good condition, making them harder to find.
Pre-independence currency notes are especially valuable because they are closely linked to India’s colonial history, making them highly desirable among serious collectors.
A Brief History of the 1-Rupee Note in India
The 1-rupee note was first introduced in 1917, featuring King George V. Its printing was stopped in 1926, then restarted in 1940, and later discontinued again in 1994.
After a gap of nearly two decades, the note was reintroduced in 2015.
One unique feature of the older versions of the 1-rupee note is that they carry the inscription “Government of India” instead of “Reserve Bank of India.” This is because the note was originally issued before the RBI was established in 1935.
Should You Check Old Notes Stored at Home?
If you come across a British-era 1-rupee note while cleaning old documents or family belongings, it could be a rare collector’s item. With proper authentication and good condition, such notes may be worth lakhs of rupees.
Before discarding old currency, it is worth taking a closer look—you might be holding a valuable piece of history.

by Jobuza Team | Jan 21, 2026 | BLOG, Trending News
PF and Investment Details: If you often find yourself switching between multiple apps and statements every month to track your bank balance, stock market investments, provident fund, and insurance policies, there is good news on the way. Soon, all your financial information could be available in one single consolidated statement.
India’s financial regulators are working on a system that aims to give individuals a complete view of their savings and investments in one place, making personal finance tracking simpler and more transparent.
No More Managing Multiple Financial Statements
At present, individuals need to log in separately to banking apps, mutual fund platforms, insurance portals, and PF websites to understand their financial position. On top of that, banks, mutual funds, and insurance companies send separate monthly or annual statements.
This scattered approach often makes it difficult to understand one’s overall wealth and financial health.
The proposed system aims to change this by offering a single monthly snapshot of a person’s entire financial portfolio, instead of multiple reports from different institutions.
Financial Regulators Are Working Together
The initiative is being led by the Securities and Exchange Board of India (SEBI). To make the system effective, SEBI is coordinating with other major financial regulators, including:
-
Reserve Bank of India (RBI)
-
Insurance Regulatory and Development Authority of India (IRDAI)
-
Pension Fund Regulatory and Development Authority (PFRDA)
The objective is to bring the entire banking, financial services, and insurance ecosystem under a common reporting framework.
Expansion of the Consolidated Account Statement (CAS)
Currently, investors already receive a Consolidated Account Statement (CAS) for their stock market and mutual fund investments. This statement typically includes:
However, the scope of the CAS is limited. Regulators are now planning to expand it so that it reflects an individual’s complete financial picture, not just market investments.
What Financial Details May Be Included
As per ongoing discussions, the expanded consolidated statement could include:
-
Bank account balances
-
Small savings scheme details
-
Insurance policy information
-
Bond investments
-
Provident Fund (PF) savings
-
National Pension System (NPS) accounts
With PFRDA’s involvement, pension-related information may also become part of the same statement.
How This Will Benefit Individuals
Once implemented, this system could help individuals:
-
Track all savings and investments from one place
-
Get a clearer understanding of their overall financial health
-
Reduce reliance on multiple apps and paper statements
-
Make better and more informed financial planning decisions
The Bigger Picture
PF and Investment Details: By bringing banking, insurance, pension, and market investments together under a single consolidated view, regulators aim to simplify financial management for millions of Indians. Although the system is still under discussion, it represents a major step toward greater transparency, convenience, and efficiency in personal finance tracking.
If implemented successfully, managing money in India could soon become far more organized and stress-free.
by Jobuza Team | Jan 19, 2026 | BLOG, Trending News
EPFO to Introduce UPI-Based PF Withdrawal Soon
Employees can withdraw the money deposited in their Provident Fund account either after retirement or, in some cases, even earlier. However, the current PF withdrawal process often takes several days. This is expected to change soon, as the Employees’ Provident Fund Organisation (EPFO) is preparing to introduce UPI-based PF withdrawals.
PF Withdrawal to Become Faster and Simpler
EPFO’s upcoming UPI facility is set to bring major relief to PF account holders. Once implemented, members will no longer need to wait days to receive their PF money. Instead, PF withdrawals will work much like regular UPI payments, allowing funds to be credited quickly in case of emergencies.
According to the latest updates, EPFO plans to roll out the UPI-based PF withdrawal feature within the next two to three months. Technical integration is currently underway in coordination with the National Payments Corporation of India (NPCI).
BHIM App to Be Used Initially
In the initial phase, PF withdrawals through UPI will be available via the BHIM app. When a member submits a PF withdrawal request on the app, the system will carry out instant backend verification.
For approved reasons such as medical emergencies or education-related needs, the claim will be processed quickly. Once verified, the PF amount will be transferred directly through the banking system, with SBI acting as the settlement bank.
Faster Than the Current PF Claim Process
At present, even an online PF advance claim of up to ₹5 lakh usually takes at least three working days to process. With the introduction of the UPI system, this waiting period is expected to reduce significantly, allowing members to access funds almost instantly when needed.
This change marks a major improvement for PF members who require quick access to their savings during urgent situations.
Limits and Safety Measures
To prevent misuse, EPFO may introduce withdrawal limits in the initial phase, in line with RBI’s existing UPI guidelines. This means members may not be able to withdraw the full PF balance through UPI at the start.
For now, the service will remain limited to the BHIM app. However, it is expected to expand to other UPI platforms in the future once the system stabilises.